Turkey’s Energy Ministry announced completed YEKA wind competitions on 2 November 2026, allocating 1,500 MW across seven areas. The investment question has therefore moved from bidding to delivery. A foreign investor considering a stake in an awarded project should establish what the project company actually holds, what it must deliver and whether the proposed investment is permitted at its current development stage.
Start with the award file, not the announcement
Obtain the tender specification, submitted offer, award decision, signed agreements and correspondence with the authority. Build an obligations schedule showing each payment, guarantee, development milestone and responsible entity. The public announcement identifies the competition outcome; it does not establish that land, construction or financing conditions are satisfied. Reconcile the financial model to the actual agreement rather than applying a headline tariff to every year of projected generation.
Confirm the investment route before paying a deposit
A share purchase, capital subscription and development-services arrangement create different rights. Map both direct and indirect ownership changes against the applicable pre-licence or licence position and tender commitments. Request a written analysis of any restriction, approval or notification before agreeing an unconditional closing. A private promise that the seller will obtain consent later should not substitute for an identified legal route and a realistic timetable.
Test whether the site can actually be built
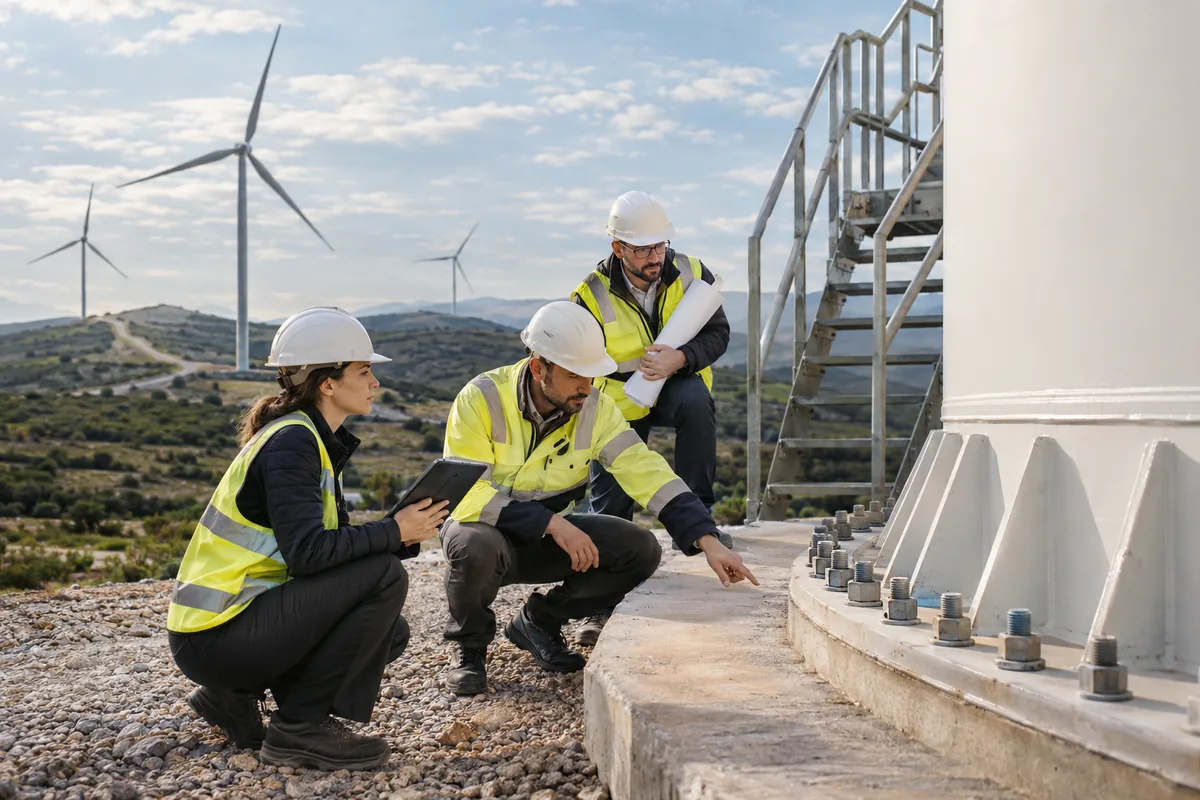
Match the awarded area to cadastral records, access routes, environmental documents and grid connection materials. Identify land that remains subject to acquisition, lease negotiation or public-authority permission. The turbine footprint is only part of the site: cables, substations and construction access can create separate dependencies. Ask the technical and legal teams to maintain one shared plan so a missing access right is reflected in both the schedule and acquisition conditions.
Allocate delivery and funding risk
Review construction, equipment supply and operations contracts together. Their delivery dates, testing standards, warranty periods and liability caps should support the project company’s commitments. Record who funds cost overruns and replacement security, and when shareholders must contribute further capital. Stress-test a delayed commissioning scenario. If additional equity is required before revenue begins, the shareholders’ agreement should explain the funding process and consequences of a failure to contribute.
Translate findings into closing conditions
Classify findings as matters to resolve before signing, conditions to satisfy before closing, or obligations that can safely continue afterwards. For a material missing permit, consider an objective condition and a long-stop date rather than a broad assurance that the project is compliant. Specify the evidence required to release escrow or pay deferred consideration. Keep a complete handover file so the operating team inherits the same obligations schedule used in the acquisition.
Investor checklist
- Award documents and the project company’s ownership chain.
- Licence status, transfer restrictions and required authority steps.
- Land, access, environmental and grid evidence.
- Funding commitments, guarantees and realistic construction dates.
- A priced risk register and objective closing evidence.
For transaction-specific support, see our M&A transaction advisory and investment legal advice.
Continue with: Buying a Solar or Wind Project in Turkey: A Legal Due Diligence Checklist; Battery Storage Projects in Turkey: What Foreign Investors Must Verify Before Acquisition.
Frequently asked questions
Is the November wind competition still open?
The cited Ministry announcement reports completed awards on 2 November 2026. Any later opportunity must be checked against a separate current notice.
Does winning an award mean the project is ready for construction?
No. Review the project-specific land, permit, connection and contractual requirements separately.
Can the buyer rely on the seller’s financial model?
Use it as an input, then reconcile assumptions to the signed project documents and independent technical review.